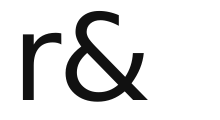
Every R&D offset that is not refundable is non-refundable. Section 67-30 makes the offset refundable only when it is worked out under item 1 of the rate table, so the non-refundable offset covers everyone else.
Two ways into it
- Turnover. Aggregated turnover of $20 million or more, counting connected entities and affiliates worldwide for the time they are connected.
- Exempt entity control. At any time in the year, one or more income tax exempt entities control the company under the connected entity test with a 50% threshold. This applies whatever the turnover.
Either way the rate is the company tax rate plus the intensity premium, and spend above $150 million earns the tax rate only.
How it is used in the return
| Step | What happens |
|---|---|
| Order | Applied after most offsets, such as the foreign income tax offset, but before refundable offsets |
| Excess | Carried forward to a later income year under Division 65 (item 35 of s 63-10(1)) |
| Condition | The company must satisfy the tax offset carry-forward rules |
Because it only reduces tax, a loss-making company with turnover above $20 million gets no cash from it at all: a carried-forward amount lowers the tax bill in a later profitable year and is never refunded. That is the gap companies nearing $20 million turnover plan around, and the reason the refundable offset matters to younger companies. Worked examples at three company sizes are in the R&D tax offset.
The 2026-27 Budget proposes, for income years from 1 July 2028, a $50 million refundable threshold and a 10-year age limit counted from a start day, with older companies under $50 million getting their tax rate plus 23 points as a non-refundable offset. That is proposed, not law; Treasury consulted on draft legislation from 10 to 28 September 2026 (see the 10-year refundable offset limit).