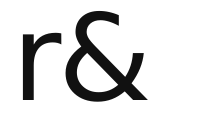
AusIndustry's application guidance puts it plainly: "The R&DTI is a self-assessment program." There is no routine approval step, so the judgement, and the risk, sit with the company.
What the company decides
Before registering, the company itself answers five questions:
- Is it an R&D entity, and is the work conducted for it rather than for someone else?
- Does each activity meet the core R&D activity test, or is it properly supporting one?
- Does any exclusion in section 355-25(2) apply?
- Which income year was each activity conducted in?
- What share of each salary, contractor bill and asset relates to the registered activities?
Registration generally proceeds on those answers as given. The company's accountant then works out the expenditure claim for the tax return.
When the answers are tested
A check can come at three points, from either regulator:
- Before registration. AusIndustry may examine activities before registering them and, if it finds them ineligible, refuse to register them.
- After registration. The Board may examine a registration on its own initiative and must do so if the Commissioner asks. A finding that an activity was not core or supporting can cover the current and earlier years, and binds the ATO if made within 4 years after the end of the income year.
- After lodgment. The ATO can review the expenditure claimed in the tax return, and can hold a refund while it checks the claim, telling the company within 30 days of lodgment.
Separately, the ATO publishes each company's claimed R&D expenditure 2 years after the financial year ends.
Reducing the risk
An examination opens with a statement of issues and usually 30 days to respond with evidence, so self-assessment rewards claims built from contemporaneous evidence. Where eligibility is genuinely unclear, an advance finding gives a binding answer before the claim; comparing that with an annual claim shows the trade-off. The registration field checker checks how a drafted answer reads against the form's limits, but it is a wording check, not an eligibility assessment.